India aspires to become an economic superpower, yet global investors increasingly ask a fundamental question: does the country offer not merely high growth, but predictable governance, shareholder protection, technological opportunity and competitive risk-adjusted returns? This tension lies at the heart of India’s foreign investment challenge. Economic expansion does not automatically translate into superior stock-market performance or sustained capital inflows. Investors compare jurisdictions, calculate after-tax returns and evaluate institutional credibility before committing funds. India’s challenge is therefore larger than attracting foreign money; it must create conditions under which capital feels confident to enter, productive enterprises can expand and investors remain committed through market volatility. The central lesson is clear: potential attracts attention, but institutional credibility earns investment.
The historical irony is striking. India and China once accounted for a substantial share of global economic output, before industrialisation and colonialism reshaped the distribution of economic power. Since the 1991 reforms, India has progressively expanded its market economy, financial infrastructure and investor participation. Market capitalisation has risen from a small base to several trillion dollars, while digital access, electronic settlement and regulatory institutions have transformed market functioning. The Securities and Exchange Board of India (SEBI) has played an important role in strengthening market oversight. Yet a larger stock market is not necessarily a better investment. Rising valuations increase expectations, narrow the margin of safety and expose weaknesses in earnings quality or corporate conduct. India must distinguish between the impressive scale of its economic transformation and the actual returns available to investors purchasing assets at prevailing prices.
Corporate governance is the decisive test of whether economic growth translates into investor confidence. Foreign investors examine the quality of disclosures, related-party transactions, promoter conduct, capital allocation and protection of minority shareholders. Concerns attributed to veteran investor discussions suggest that governance weaknesses may affect a meaningful section of listed companies, although any estimate that 20–30 per cent of index constituents fail specified integrity standards requires independent verification. The larger point remains valid: governance is an economic variable, not merely an ethical aspiration. When investors doubt the reliability of corporate information or the fairness of regulatory enforcement, they demand a higher risk premium or move elsewhere. India’s financial ambitions therefore require stronger disclosure standards, consistent enforcement and credible remedies for shareholder grievances. No country can command a lasting valuation premium simply because its growth prospects appear attractive; that premium must be justified by the quality of its institutions and enterprises.
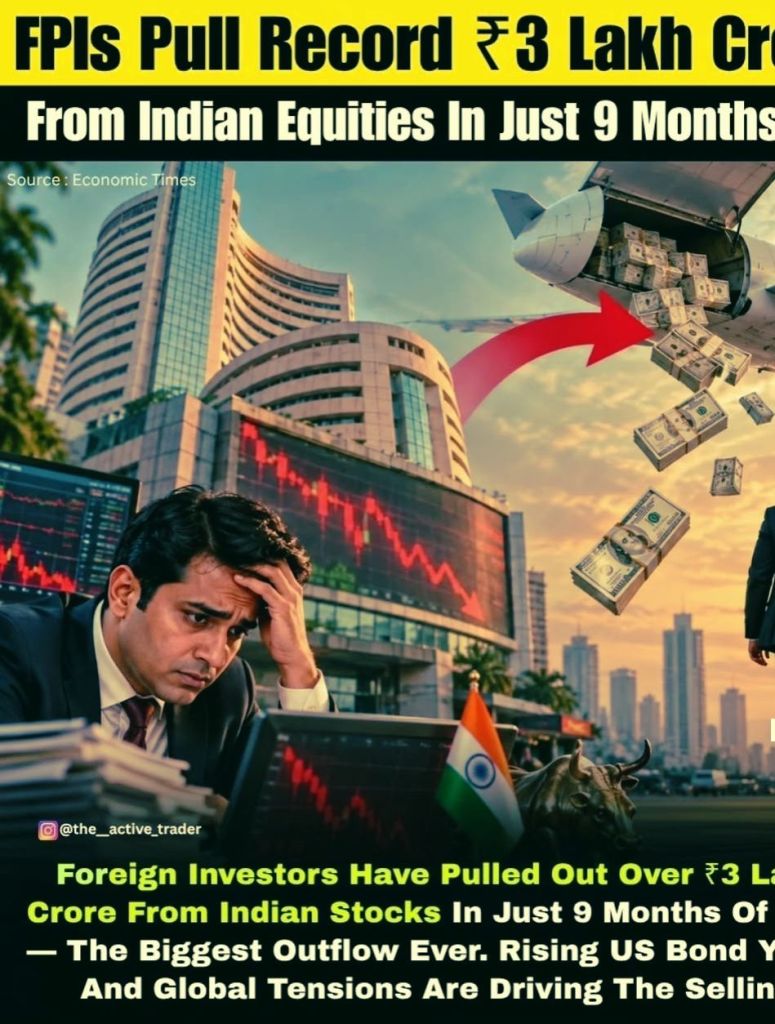
The foreign portfolio investor sell-off must be understood as the cumulative outcome of valuation pressures, global competition and domestic uncertainties. Following the market highs of September 2024, elevated valuations reduced the margin of safety. Changes in capital-gains taxation, rupee uncertainty and geopolitical developments added to investor calculations, while higher crude prices increased India’s external vulnerability. Simultaneously, global investment enthusiasm shifted towards artificial intelligence, semiconductors and advanced computing. Taiwan and South Korea offer investors established exposure to electronics and semiconductor supply chains, whereas India’s listed markets provide comparatively limited exposure to some of these hardware-intensive technologies. Currency depreciation further complicates returns: an Indian asset may appreciate in rupees while delivering a weaker return in dollars. Higher US Treasury yields also provide an alternative to emerging-market risk. India must consequently compete on valuation, technological opportunity and credibility—not assume that global investors will remain committed regardless of alternatives.
Taxation and regulatory predictability are equally important. Investors can accommodate reasonable tax obligations, but uncertainty over interpretation, compliance and retrospective disputes can undermine confidence. India should pursue stable capital-gains rules, efficient treaty administration and timely resolution of tax disputes without compromising legitimate public revenue. GIFT City offers an opportunity to strengthen India’s position as an international financial centre through competitive regulation and efficient financial services. Equally, foreign direct investment requires attention beyond headline inflows. Gross investment figures do not necessarily reveal net retention, reinvestment or capital repatriation; the figures cited in the underlying briefing for April–December 2025 require verification before firm conclusions can be drawn. Manufacturing investors need timely approvals, reliable infrastructure, accessible land, skilled workers and predictable incentives. A single-window clearance mechanism must deliver decisions within defined timelines, rather than merely provide a digital interface. Capital stays where businesses can execute plans without avoidable administrative friction.
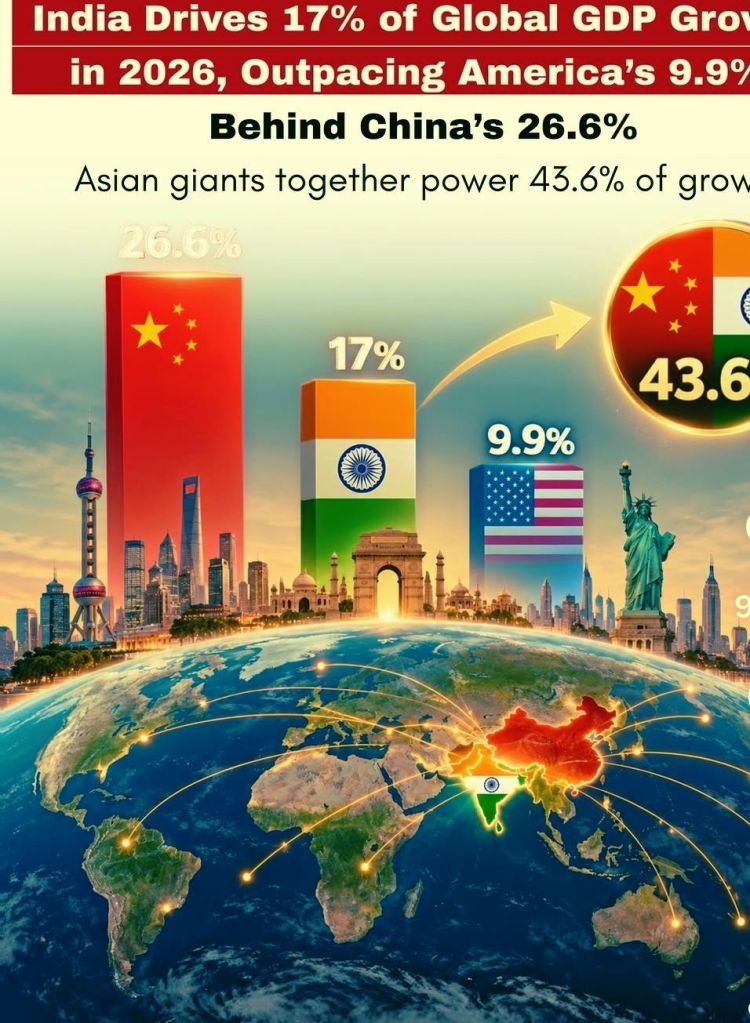
The employment and technology dimensions make these reforms urgent. Millions of young Indians enter the labour market over time, and the country must expand productive employment to convert its demographic potential into an economic dividend. Manufacturing, electronics, renewable energy, advanced materials and deep technology can strengthen exports while creating skilled jobs. Achieving this requires research institutions, patient domestic capital, industrial infrastructure and closer collaboration between universities and enterprises. India should also deepen its participation in global AI and semiconductor ecosystems instead of relying predominantly on software services and imported hardware. Meanwhile, passive investors deserve greater transparency regarding index turnover, transaction costs, tracking error and taxation, all of which influence realised returns. India should mobilise domestic savings for innovation, improve corporate accountability and develop financing mechanisms that support emerging industries. The objective is not to imitate East Asian economies mechanically, but to learn from their sustained commitment to manufacturing capabilities, skills and technological development.
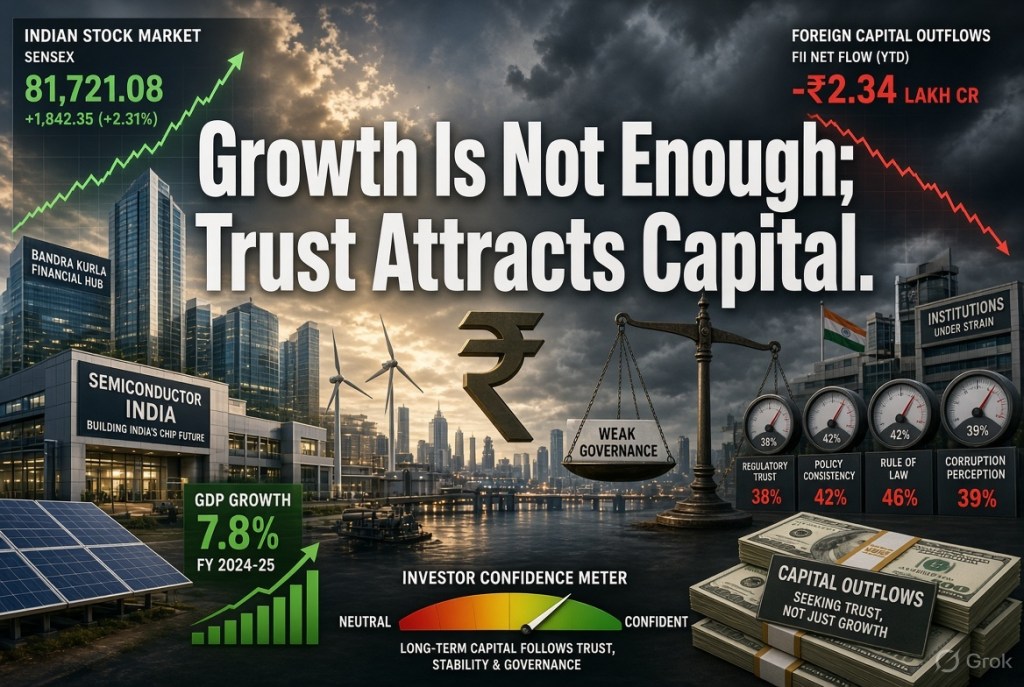
India’s response must therefore be comprehensive: strengthen corporate governance, stabilise the policy environment, communicate currency policy credibly, accelerate industrial execution and broaden technological competitiveness. Foreign portfolio investment and foreign direct investment serve different purposes, but both depend on institutional confidence and predictable rules. India need not promise uninterrupted market gains or defend an arbitrary exchange rate. It must demonstrate that investors can assess risks transparently, enterprises can scale efficiently and contractual and shareholder rights will be respected. The ultimate measure of economic leadership is not the volume of capital entering during favourable global conditions, but the productive investment retained when markets turn uncertain. India’s growth story remains compelling; however, demographic optimism and headline GDP expansion cannot indefinitely justify a valuation premium. The world is not short of interest in India’s potential—it is waiting for stronger evidence that this potential can be converted into reliable returns.
VISIT ARJASRIKANTH.IN FOR MORE INSIGHTS

