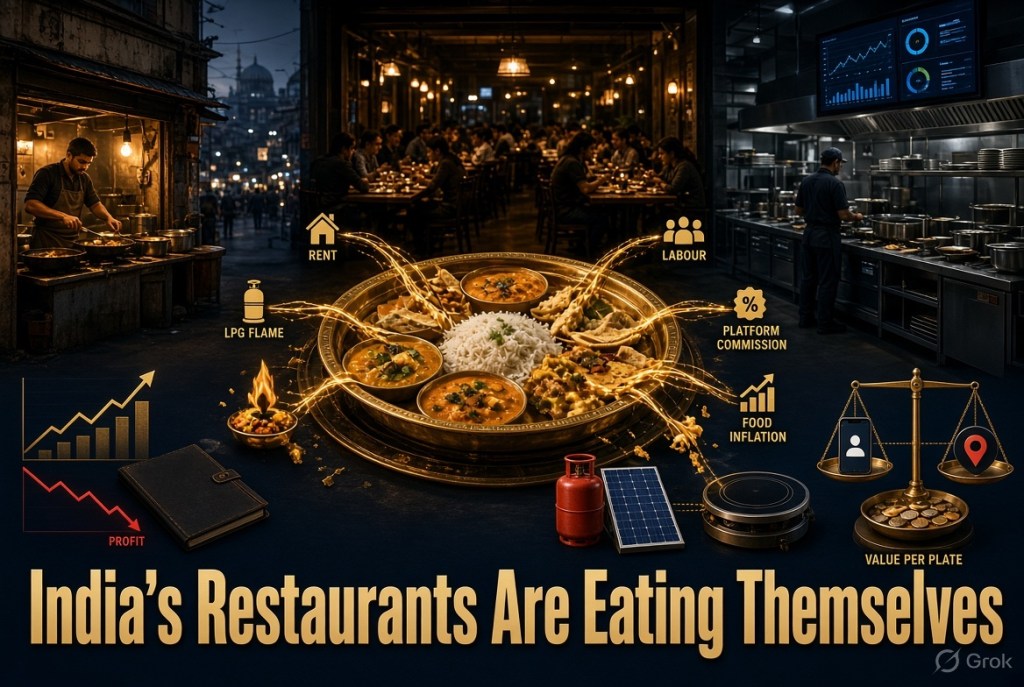
India’s restaurant industry is experiencing something far more consequential than a temporary fuel crisis. The disruption of 2026 has exposed the fragile architecture beneath a food-services economy estimated at $65–70 billion, where organised chains and digital-first brands continue to expand even as thousands of independent restaurants struggle for survival. Failure rates among standalone restaurants are estimated at 73–85% within five years. The paradox is striking: India is eating out, ordering in and experimenting with new cuisines more than ever, yet the economics of feeding India are becoming progressively harder. The crisis, therefore, is not simply about demand. It is about whether the existing restaurant business model can survive its own cost structure.
The immediate shock came from geopolitics. The closure of the Strait of Hormuz disrupted access to the Persian Gulf, from which India sources the overwhelming majority of its imported LPG. With India importing more than 60% of its LPG requirement, commercial kitchens suddenly found themselves competing with households for scarce fuel. Commercial cylinders became dramatically more expensive in parallel markets, while restaurants were forced to ration consumption, shift to alternative fuels or temporarily close. Nearly one-third of restaurants were reportedly unable to operate at full capacity, with standalone establishments suffering revenue losses of 15–25%. The estimated industry-wide monthly loss has reached extraordinary levels. Yet LPG merely detonated a problem that had been accumulating quietly for years.
The deeper crisis is the margin squeeze created by the K-shaped consumer. Food inflation has pushed up the cost of edible oil, dairy, proteins, packaging and other inputs, while consumers have simultaneously become more price-sensitive. Quick commerce has trained customers to expect convenience, discounts and low prices almost instantly. Restaurants, however, cannot indefinitely pass higher costs to customers without damaging already fragile repeat-purchase behaviour. The result is an extraordinary contradiction: customers demand better ingredients, healthier food and superior experiences while resisting corresponding price increases. A restaurant can therefore have full tables and rising digital orders and still lose money. Revenue has become an increasingly poor proxy for economic health.
Then comes the real-estate guillotine. Prime locations in Mumbai, Delhi NCR and other metros can command rents approaching those of global commercial centres despite radically different purchasing-power conditions. For an independent restaurant, rent is not merely an expense; it is a permanent claim on future revenue. Add deposits, interiors, kitchen equipment, licences and customer-acquisition costs, and working capital can disappear before the first profitable month arrives. Franchises possess a structural advantage: procurement networks, corporate bargaining power, standardised technology and the ability to negotiate better locations. Independents buy ingredients at volatile market prices, pay premium rents and frequently depend on third-party platforms for customer acquisition. They are effectively competing against companies that possess an entirely different economic machine.
The war for talent compounds the problem. Hospitality employee turnover is estimated at nearly 80%, as long hours, demanding working conditions and relatively modest entry-level wages collide with the extraordinary attraction of the gig economy and quick-commerce platforms. A trained kitchen employee can leave overnight, taking institutional knowledge with them. This exposes another weakness of the traditional restaurant: excessive dependence on individuals rather than systems. Franchised chains increasingly counter this through standard operating procedures, modular kitchen design, centralised preparation, training academies and technology-enabled workflows. The future restaurant will resemble less a chef-dependent craft workshop and more a carefully engineered production system—without necessarily sacrificing culinary creativity.
Technology, however, cannot solve a fundamentally distorted ecosystem unless the economics change. Delivery platforms have become indispensable to restaurant discovery and demand generation, but commissions, discounts and associated charges can consume 25–30% or more of order value. A restaurant may therefore generate impressive gross sales while surrendering a disproportionate share of the transaction to intermediaries. The strategic lesson is not that platforms must disappear; it is that dependency must disappear. Restaurants need a hybrid architecture combining aggregators, direct ordering, loyalty programmes, first-party customer data and alternative logistics providers. The restaurant that owns the customer relationship owns a strategic asset; the restaurant that merely receives an anonymous order owns very little.
The answer also lies inside the kitchen. Menu engineering, SKU rationalisation and AI-driven inventory management can transform invisible leakage into measurable savings. A smaller menu built around common raw materials reduces wastage, simplifies procurement and improves consistency. Cloud-based POS systems linked to predictive demand forecasting can monitor portions, inventory, labour deployment and channel profitability in real time. Standardised recipes and portion controls can significantly reduce food waste and food-cost variance. The critical shift is from the traditional month-end question—“How much did we sell?”—to a more sophisticated daily question: “Which transaction, dish, customer and channel actually created value?”
The 2026 crisis also offers an unexpected opportunity to redesign the geography of Indian food services. Tier-II and Tier-III cities are emerging as the next battlefield, offering lower real-estate costs, expanding disposable incomes and increasingly sophisticated consumers. Cities such as Pune and emerging commercial centres including GIFT City demonstrate how consumption can migrate beyond traditional metropolitan clusters. But expansion cannot simply transplant a Delhi or Mumbai format into a smaller city. Successful operators will localise menus, pricing, sourcing and store formats. Simultaneously, kitchens must become energy-resilient through induction, electric griddles, efficient ovens, PNG where available and dual-fuel capability. Energy diversification should become as fundamental to kitchen design as fire safety.
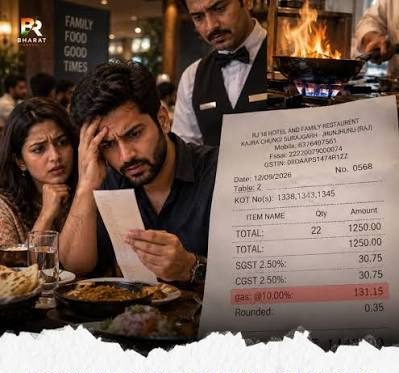
The regulatory architecture deserves equal attention. The 5% GST regime without Input Tax Credit can leave restaurants unable to offset taxes embedded in rent, equipment, renovation and other inputs, compressing already thin margins. Lengthy liquor-licensing processes can strand substantial capital in non-operational establishments. These are not merely administrative inconveniences; they influence investment decisions, employment and the survival probability of small enterprises. Policymakers therefore need to view restaurants not simply as consumption businesses but as major urban employers, tourism infrastructure and contributors to the services economy.
India’s foodservice opportunity remains enormous, with the market projected to approach $150 billion by FY31. The paradox is that the winners of this expansion may not be those who open the most outlets or generate the largest order volumes. They will be those who understand the economics of every plate, every employee, every square foot and every customer. The LPG shock has therefore delivered an uncomfortable but valuable message: India’s restaurant industry does not merely need more customers—it needs a better business model. The next generation of Indian restaurants will be built not on cheap fuel, expensive real estate and borrowed customers, but on resilience, technology, direct relationships, disciplined unit economics and the one ingredient that cannot be outsourced—institutional intelligence.
VISIT ARJASRIKANTH.IN FOR MORE INSIGHTS

