One year after the launch of GST 2.0 on 22 September 2025, India’s indirect-tax architecture looks dramatically cleaner—but the economy beneath the tax table remains stubbornly complicated. The four principal slabs were compressed into a 5% merit rate and an 18% standard rate, with a 40% de-merit rate for selected luxury and sin goods. Individual life and health insurance premiums were brought under a zero-GST regime, while several everyday products received substantial rate reductions. Yet the first anniversary reveals a distinction that tax policy often obscures: reducing the tax imposed on a product is not the same thing as reducing the price ultimately paid for it. GST 2.0 has simplified the architecture; the harder question is whether its benefits reliably travel through the market to the household.
The evidence emerging from the National Institute of Public Finance and Policy makes that distinction unusually visible. Its study of 355 CPI items compared average prices before and after the September 2025 restructuring and found sharply divergent transmission. Motor vehicles, air conditioners and other discretionary durables experienced meaningful price declines. Cars and jeeps, whose GST rate fell from 28% to 18%, recorded a 7.52% decline in CPI; air conditioners fell 6.4%, while motorcycles and scooters declined 5.19%. (NIPFP) These are not trivial movements. They suggest that in markets characterized by large-ticket purchases, brand competition and discretionary demand, businesses had stronger incentives to pass at least part of the tax benefit to consumers. A customer can postpone buying a car, compare models, bargain across dealers or switch brands. Competitive pressure therefore becomes an important transmission mechanism.
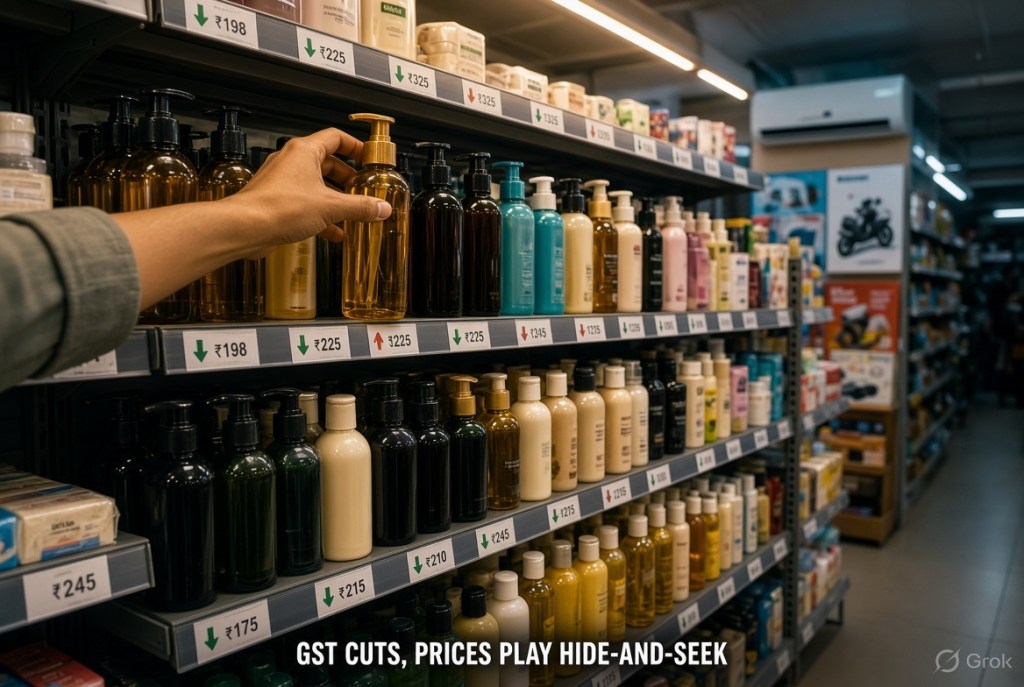
At the household shelf, however, the GST story becomes far more paradoxical. Hair oil, despite its GST rate falling from 18% to 5%, recorded a 2.77% increase in CPI in NIPFP’s comparison. Shampoo and related products also rose by around 1%, while several other personal-care items recorded modest increases. (NIPFP) This does not establish that GST reductions had no effect; it demonstrates something economically more interesting: tax policy operates inside markets rather than above them. Input costs, inventory purchased before the rate change, logistics, distributor margins, commodity prices, brand positioning and pricing strategies can absorb, delay or offset a reduction in indirect tax. The tax department may change the rate overnight; the market adjusts through thousands of contracts, inventories and commercial decisions.
That produces a revealing divide between discretionary consumption and essential consumption. A household can postpone a car purchase, but postponing toothpaste is considerably harder. A consumer buying a refrigerator can compare brands and wait for a discount; a family purchasing soap, shampoo or medicines has fewer strategic responses to small price movements. Demand elasticity therefore becomes an invisible participant in tax transmission. Where consumers possess the power to walk away, competition can force businesses to share the tax benefit. Where demand is relatively inelastic, the benefit can be distributed differently across the supply chain. The crucial question consequently shifts from “Was GST reduced?” to “Who captured the economic value created by that reduction?” That value may reach consumers, manufacturers, distributors or retailers—or be divided among them.
The Nandini ghee episode illustrates another complication: markets do not freeze on the day a tax reform begins. A reported reduction in the price of a litre of ghee after GST rationalization was subsequently followed by a price increase attributed by the dairy federation to broader market pressures. Whatever the individual product’s trajectory, the analytical lesson is larger. Commodity prices, weather, international markets, energy costs, logistics and inflation continue moving after a tax announcement. A four-month pre- and post-reform comparison can reveal patterns of transmission, but it cannot by itself establish a permanent causal relationship. NIPFP itself describes its findings as evidence of varying degrees of price adjustment rather than a universal rule. (NIPFP) Tax reform therefore enters a moving economy; it does not operate inside a laboratory.
GST 2.0’s strongest institutional achievement may consequently lie elsewhere: digitalisation. Deloitte’s 2026 GST@9 survey of about 1,100 business leaders found more than 99% reporting a positive or neutral experience with GST, with compliance digitalization identified by 69% as its biggest success. Yet the same survey reveals the unfinished business: 87% sought greater clarity in tax interpretation, 77% identified refund delays, and 57% flagged input-tax-credit disputes. The paradox is striking. India has digitized the machinery of compliance without completely eliminating the uncertainty surrounding compliance. The paper file may have disappeared, but ambiguity can simply migrate into interpretation, reconciliation, refunds, audits and litigation. A digital tax system is not necessarily a predictable tax system.
For smaller enterprises, this distinction is even more important. Digitalisation can dramatically reduce transaction costs for businesses with accounting teams, software and professional advisers, but the same architecture can become burdensome when compliance capacity is limited. Deloitte’s survey points towards precisely this next frontier: automated interest on delayed refunds, simplified input-tax-credit rules, invoice-based eligibility, quarterly payment mechanisms and more uniform audits. (Deloitte) These are not glamorous reforms. They lack the political drama of announcing a new tax slab. But they determine working capital, business survival and investment decisions every day. A tax system should not merely make it easier for government to collect; it must also make it easier for compliant businesses to understand, claim and recover what the law permits.
The federal dimension cannot be ignored either. GST was created as a grand fiscal bargain between the Union and the States, but rate rationalization inevitably interacts with state revenue, compensation arrangements and fiscal autonomy. The next stage therefore requires less fascination with headline rate cuts and greater attention to the plumbing of the system: predictable refunds, faster dispute resolution, simpler ITC rules, automated processes, harmonized audits and clearer interpretation. The GST Council’s forthcoming process-reform agenda reflects this shift, with the October 2026 meeting expected to focus on procedural reforms rather than another major rate restructuring. GST 2.0 has consequently moved India substantially closer to a simpler tax architecture, but simplicity on the tax chart is only the beginning. The real GST revolution will be completed when the benefit travels seamlessly from rate cut to invoice, invoice to supply chain, and supply chain to household. Until then, India may have simplified the tax table without fully simplifying the economic journey that begins there.
VISIT ARJASRIKANTH.IN FOR MORE INSIGHTS

